Understanding the relationship between credit scores and car insurance in Nevada is crucial for drivers seeking to navigate their insurance options effectively. Many are unaware that their credit history can significantly influence their insurance premiums, as Nevada insurance providers often consider credit scores when determining rates. This article will explore how credit affects insurance rates in Nevada, providing insights into the intricate dynamics between credit scores and insurance costs. We will delve into the role of Nevada insurance and credit, highlighting the importance of maintaining a good credit score for securing favorable insurance rates. Additionally, we will outline key takeaways regarding insurance rates and credit score correlations, and address frequently asked questions about this vital topic. By understanding these factors, Nevada residents can make informed decisions that may lead to significant savings on their car insurance premiums. For further reading, consider checking out Consumer Financial Protection Bureau for more insights on credit management.
Understanding Credit Scores and Car Insurance in Nevada
What Are Credit Scores?
Credit scores are numerical representations of an individual’s creditworthiness, reflecting their likelihood of repaying borrowed funds. Ranging from 300 to 850, these scores are calculated based on several factors, including payment history, credit utilization, length of credit history, types of credit used, and new credit inquiries. A higher score indicates better credit health, which plays a crucial role in the financial landscape, influencing everything from loan approvals to interest rates.
How Credit Scores Affect Car Insurance Rates in Nevada
In Nevada, credit scores affect car insurance rates significantly. Insurance companies often use credit scores as a factor in determining premiums, believing that individuals with higher credit scores are less likely to file claims. Consequently, those with lower scores may face higher insurance rates. This practice is rooted in statistical analysis, indicating a correlation between creditworthiness and the likelihood of filing a claim.
For residents seeking affordable rates, understanding the relationship between insurance rates and credit score is vital. In Nevada, insurers can utilize credit information to assess risk, leading to potential savings for those with strong credit histories. Therefore, maintaining a good credit score can directly impact the cost of car insurance, making it essential for individuals to monitor their credit health regularly.
To optimize insurance costs, consider reviewing your credit report for errors, paying bills on time, and reducing debt. These actionable steps can not only improve your credit score but also lead to better insurance rates in Nevada. Additionally, it’s advisable to shop around and compare quotes from different providers to ensure you’re getting the best deal possible.
The Role of Nevada Insurance and Credit
State Regulations on Credit Scores
In Nevada, regulations concerning the use of credit scores in determining car insurance rates are designed to ensure fair practices among insurers. The state allows insurance companies to consider credit history when assessing risk and setting premiums. However, the Nevada Division of Insurance mandates that insurers must provide a clear explanation to policyholders regarding how their credit scores impact their rates. This transparency helps consumers understand the connection between credit scores car insurance Nevada and their overall insurance costs.
Specifically, Nevada law requires that any adverse action taken based on credit information must be communicated to the consumer. This means if a driver faces higher premiums due to their credit score, the insurer must inform them and provide a rationale. This regulation aims to protect consumers from unexpected rate increases while promoting responsible financial behaviors.
Insurance Companies’ Use of Credit Scores
Insurance companies in Nevada typically assess credit scores as part of their underwriting process. They believe that individuals with better credit histories are less likely to file claims, thus presenting a lower risk. This correlation between how credit affects insurance is widespread across the industry, not just limited to Nevada.
When evaluating insurance rates and credit scores, insurers may use a variety of factors, including payment history, credit utilization, and the length of credit accounts. Each insurer has its own method for weighing these factors, which can result in varying premiums even for consumers with similar credit profiles. Consequently, it is prudent for policyholders to shop around and compare quotes from multiple companies, as different insurers may interpret credit data differently.
Understanding the role of credit scores in car insurance can empower Nevada residents to take proactive steps in managing their financial health and potentially lower their insurance costs. For those looking to improve their credit standing, paying bills on time and reducing outstanding debts can lead to better credit scores, which may, in turn, influence future insurance rates positively.
How Credit Affects Insurance Rates in Nevada
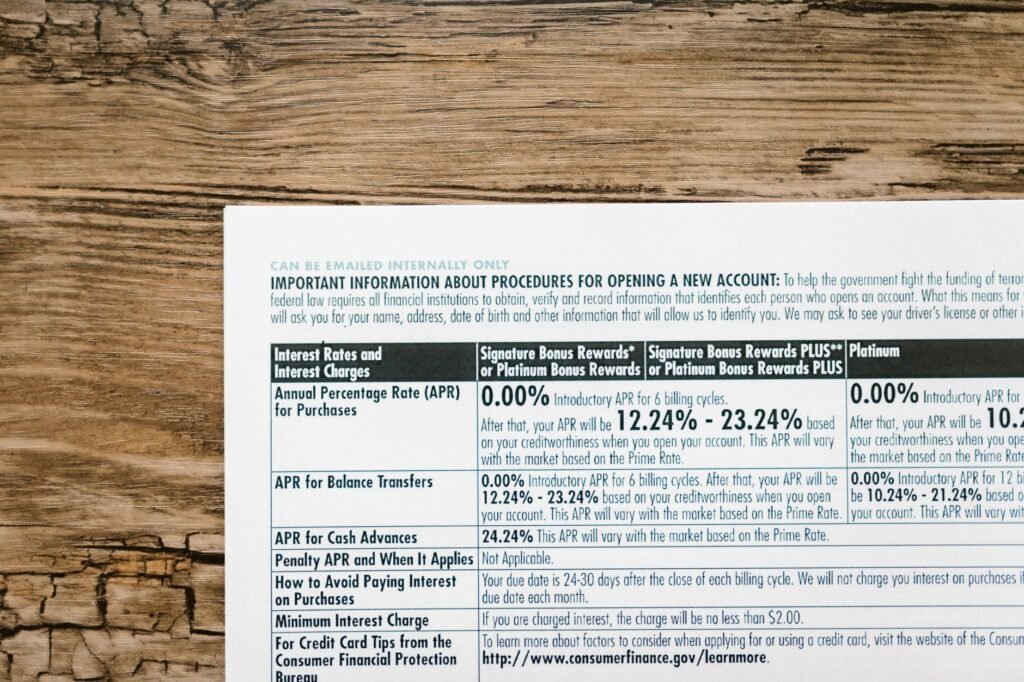
Your credit score can significantly influence your insurance premiums, particularly in Nevada. Insurance companies often use credit scores as a predictive measure of risk, which means that lower credit scores can lead to higher insurance rates. This practice raises questions for many drivers regarding how credit affects insurance and what can be done to mitigate potential costs.
The Impact of Poor Credit
In Nevada, the relationship between credit scores and car insurance rates is clear: individuals with poor credit often face elevated premiums. According to a study by the Consumer Financial Protection Bureau, drivers with a poor credit score may pay up to 50% more for their car insurance compared to those with excellent credit scores. For example:
- Excellent Credit (750+): Typically, these individuals may receive the lowest rates available.
- Good Credit (700-749): Slightly higher rates, but still competitive.
- Fair Credit (650-699): Noticeable increases in premiums.
- Poor Credit (below 650): Significant hikes in insurance costs, potentially leading to being quoted rates beyond affordability.
Understanding these dynamics is crucial for drivers in Nevada looking to manage their insurance costs effectively. Impact of Credit Scores on Car Insurance Rates in Nevada
Improving Your Credit Score for Better Rates
Improving your credit score can be a game changer in reducing your insurance rates. Here are some actionable tips to enhance your credit profile:
- Pay Your Bills on Time: Timely payments are crucial as payment history is a significant factor in your credit score.
- Reduce Debt: Aim to lower credit card balances to improve your credit utilization ratio.
- Check Your Credit Report: Regularly review your credit report for errors and dispute any inaccuracies.
- Avoid Opening New Accounts: Each new account can temporarily lower your score; thus, it’s best to avoid new credit inquiries when possible.
By focusing on these strategies, you can improve your insurance rates and credit score, which is vital for obtaining lower premiums on car insurance in Nevada. Improved credit may not only save you money on insurance but also provide better loan terms and interest rates in other financial areas. Credit Score Car Insurance Nevada: Understanding the Impact
Insurance Rates and Credit Score: Key Takeaways
Summary of Key Findings
The relationship between credit scores and car insurance rates in Nevada is significant. Numerous studies have shown that individuals with higher credit scores typically enjoy lower insurance rates. This correlation exists because insurers view credit scores as a predictor of risk; those with better credit histories are often seen as more responsible and less likely to file claims. According to NAIC, states like Nevada are increasingly factoring in credit scores when determining insurance premiums.
Understanding how credit affects insurance is crucial for Nevada residents. Insurers in the state utilize credit information to create risk profiles, which can influence the rates you pay for car insurance. Lower credit scores can lead to higher premiums, making it essential to maintain a good credit history to secure the best possible rates.
Practical Steps to Take for Better Credit Scores and Car Insurance in Nevada
Improving your credit scores not only benefits your financial health but also can lead to lower insurance rates. Here are actionable steps you can take:
- Regularly Check Your Credit Report: Obtain free copies of your credit report from AnnualCreditReport.com and check for errors or discrepancies.
- Pay Bills on Time: Consistently paying your bills, including credit cards and loans, can positively impact your credit score.
- Reduce Debt: Lowering your total debt load can improve your credit utilization ratio, which is a key factor in credit scoring.
- Avoid New Hard Inquiries: Limiting the number of new credit applications can prevent unnecessary dips in your score.
- Consider Credit Counseling: If you’re struggling, seek assistance from a certified credit counselor to create a strategy for improvement.
By following these steps, you can enhance your credit score and potentially lower your insurance rates. Remember, maintaining a strong credit profile can lead to significant savings on your insurance rates and credit score in Nevada.
Frequently Asked Questions About Credit Scores and Car Insurance in Nevada
How Do Credit Scores Affect Car Insurance Rates in Nevada?
In Nevada, insurance companies frequently use credit scores as one of the factors to determine car insurance premiums. Higher credit scores often correlate with lower insurance rates, as insurers view individuals with better credit as less risky. Conversely, those with lower credit scores may face higher insurance rates due to the perceived risk.
What Is the Relationship Between Credit Scores and Car Insurance in Nevada?
The relationship between credit scores and car insurance in Nevada is significant. Insurers assess credit histories to gauge the likelihood of filing claims. Studies have shown that individuals with poor credit are more likely to file claims, which leads to higher premiums. Therefore, maintaining a good credit score can help you secure more favorable insurance rates.
Can I Improve My Credit Score to Lower My Insurance Rates?
Yes, improving your credit score can positively impact your insurance rates. Here are some actionable steps to enhance your credit:
- Pay Bills on Time: Timely payments contribute significantly to your credit score.
- Reduce Debt: Keeping credit utilization low can improve your score.
- Monitor Your Credit Report: Check for errors and dispute any inaccuracies.
- Avoid Opening New Lines of Credit: Too many inquiries can negatively affect your score.
Will My Insurance Company Notify Me of Changes in My Credit Score?
Insurance companies typically review credit scores at the time of policy renewal or when you apply for a new policy. If there are significant changes in your credit score that could affect your premium, they may notify you. It’s wise to check your own credit score periodically to understand how it may impact your insurance rates.
What If I Don’t Have a Credit History?
If you lack a credit history, some insurers may use alternative methods to assess your risk. This could include your driving record or claims history. However, not having a credit score may lead to higher premiums, as insurers typically prefer to evaluate credit when determining insurance rates and credit score.
Understanding how credit affects insurance can empower you to make informed decisions about both your credit and your insurance coverage. By improving your credit score, you may not only secure better insurance rates but also enjoy other financial benefits.
Understanding the relationship between credit scores and car insurance rates in Nevada is crucial for consumers looking to save on their premiums. As highlighted, how credit affects insurance is a significant factor in determining insurance rates and credit score. Those with higher credit scores often enjoy lower rates, while individuals with poor credit may face higher costs for Nevada insurance and credit. By improving your credit score, you can potentially reduce your insurance expenses, making it a wise financial goal.
To take the next step, consider reviewing your credit report and identifying areas for improvement. This proactive approach can help you secure better insurance rates in the future. Additionally, reach out to various insurance providers to understand how they factor credit into their pricing. This knowledge will empower you to make informed decisions regarding your car insurance in Nevada, ensuring you get the best value for your coverage.
“`html
How do credit scores impact car insurance rates in Nevada?
In Nevada, insurance companies often use credit scores to help determine car insurance rates. A higher credit score typically indicates lower risk, which can lead to lower premiums. Conversely, a poor credit score may signal a higher risk, resulting in higher insurance rates. This is because insurers believe that individuals with better credit management are less likely to file claims.
What is the relationship between Nevada insurance and credit?
The relationship between Nevada insurance and credit is significant, as many insurers consider credit scores when calculating premiums. This practice is based on the idea that a person’s financial behavior can predict their likelihood of filing insurance claims. Thus, maintaining a good credit score can be beneficial for individuals seeking affordable car insurance in Nevada.
Can I get car insurance with a poor credit score?
Yes, you can still obtain car insurance with a poor credit score, but you may face higher premiums. Insurers may view you as a higher risk, which can lead to increased rates. However, some companies specialize in providing coverage for individuals with less-than-perfect credit, so it is advisable to shop around for the best options available.
How much can a low credit score increase my insurance rates?
The impact of a low credit score on insurance rates can vary significantly among insurers. On average, individuals with poor credit scores may see their premiums increase by 20 to 50 percent compared to those with good credit. It’s important to compare quotes from different companies to understand how credit scores car insurance Nevada affects your specific rates.
What steps can I take to improve my credit score for insurance?
To improve your credit score for insurance purposes, start by checking your credit report for errors and disputing any inaccuracies. Pay down existing debts and make all future payments on time. Reducing your credit utilization and avoiding new debt can also help. Regularly monitoring your credit can provide insights into further improvements.
Are there alternatives to using credit scores for insurance rates?
Yes, some insurance providers offer alternatives to using credit scores when determining rates. These may include factors such as driving history, claims history, and the type of vehicle. Additionally, some companies may consider factors like occupation or education level, so it’s worth exploring different insurers to find one that aligns with your preferences.
“`